

Our approach
How share option schemes work
A share option gives the holder the right to buy shares in the company at a fixed price, at a future point. Done well, it creates a direct link between the value a person helps build and the reward they receive when that value is realised.
For most qualifying SMEs, the right starting point is an EMI (Enterprise Management Incentive) scheme. EMI is a government-approved arrangement that comes with significant tax advantages for both the company and the option holder. Options are granted at an agreed market value, HMRC is notified, and when the options are eventually exercised, employees benefit from entrepreneurs' relief on the gain.
Not every company qualifies for EMI. Where EMI isn't available, we advise on alternative arrangements including unapproved options and growth shares, and help you find the structure that achieves what you're trying to do.
How we work with you
We agree a fixed fee before any work starts, so you know the cost upfront.
The first step is understanding what you're trying to achieve: who you want to incentivise, when you expect options to vest, what exit or liquidity events you're planning for, and whether your company qualifies for EMI. We'll walk you through the key decisions, explain the tax treatment for the company and the option holders, and make sure the scheme is structured to do what you intend.
We handle the legal side: the scheme documentation, option agreements and plan rules. The HMRC valuation is typically managed by your accountant or a specialist tax adviser, and we work alongside them throughout. If you don't yet have someone with EMI experience on your side, we can make introductions.
Who we work with
We work with founder-led agencies, tech businesses and high-growth companies that want to use equity to attract and retain the right people. That might be a business putting a scheme in place for the first time, a company that's growing quickly and needs to compete on compensation, or a founder who wants to make sure the team shares in the upside ahead of an exit or investment round.
We also work with individuals who have been offered options and want to understand what they're agreeing to before they sign.
Pricing

Fixed-fee project

Available via subscription
Case Studies

Meet the team
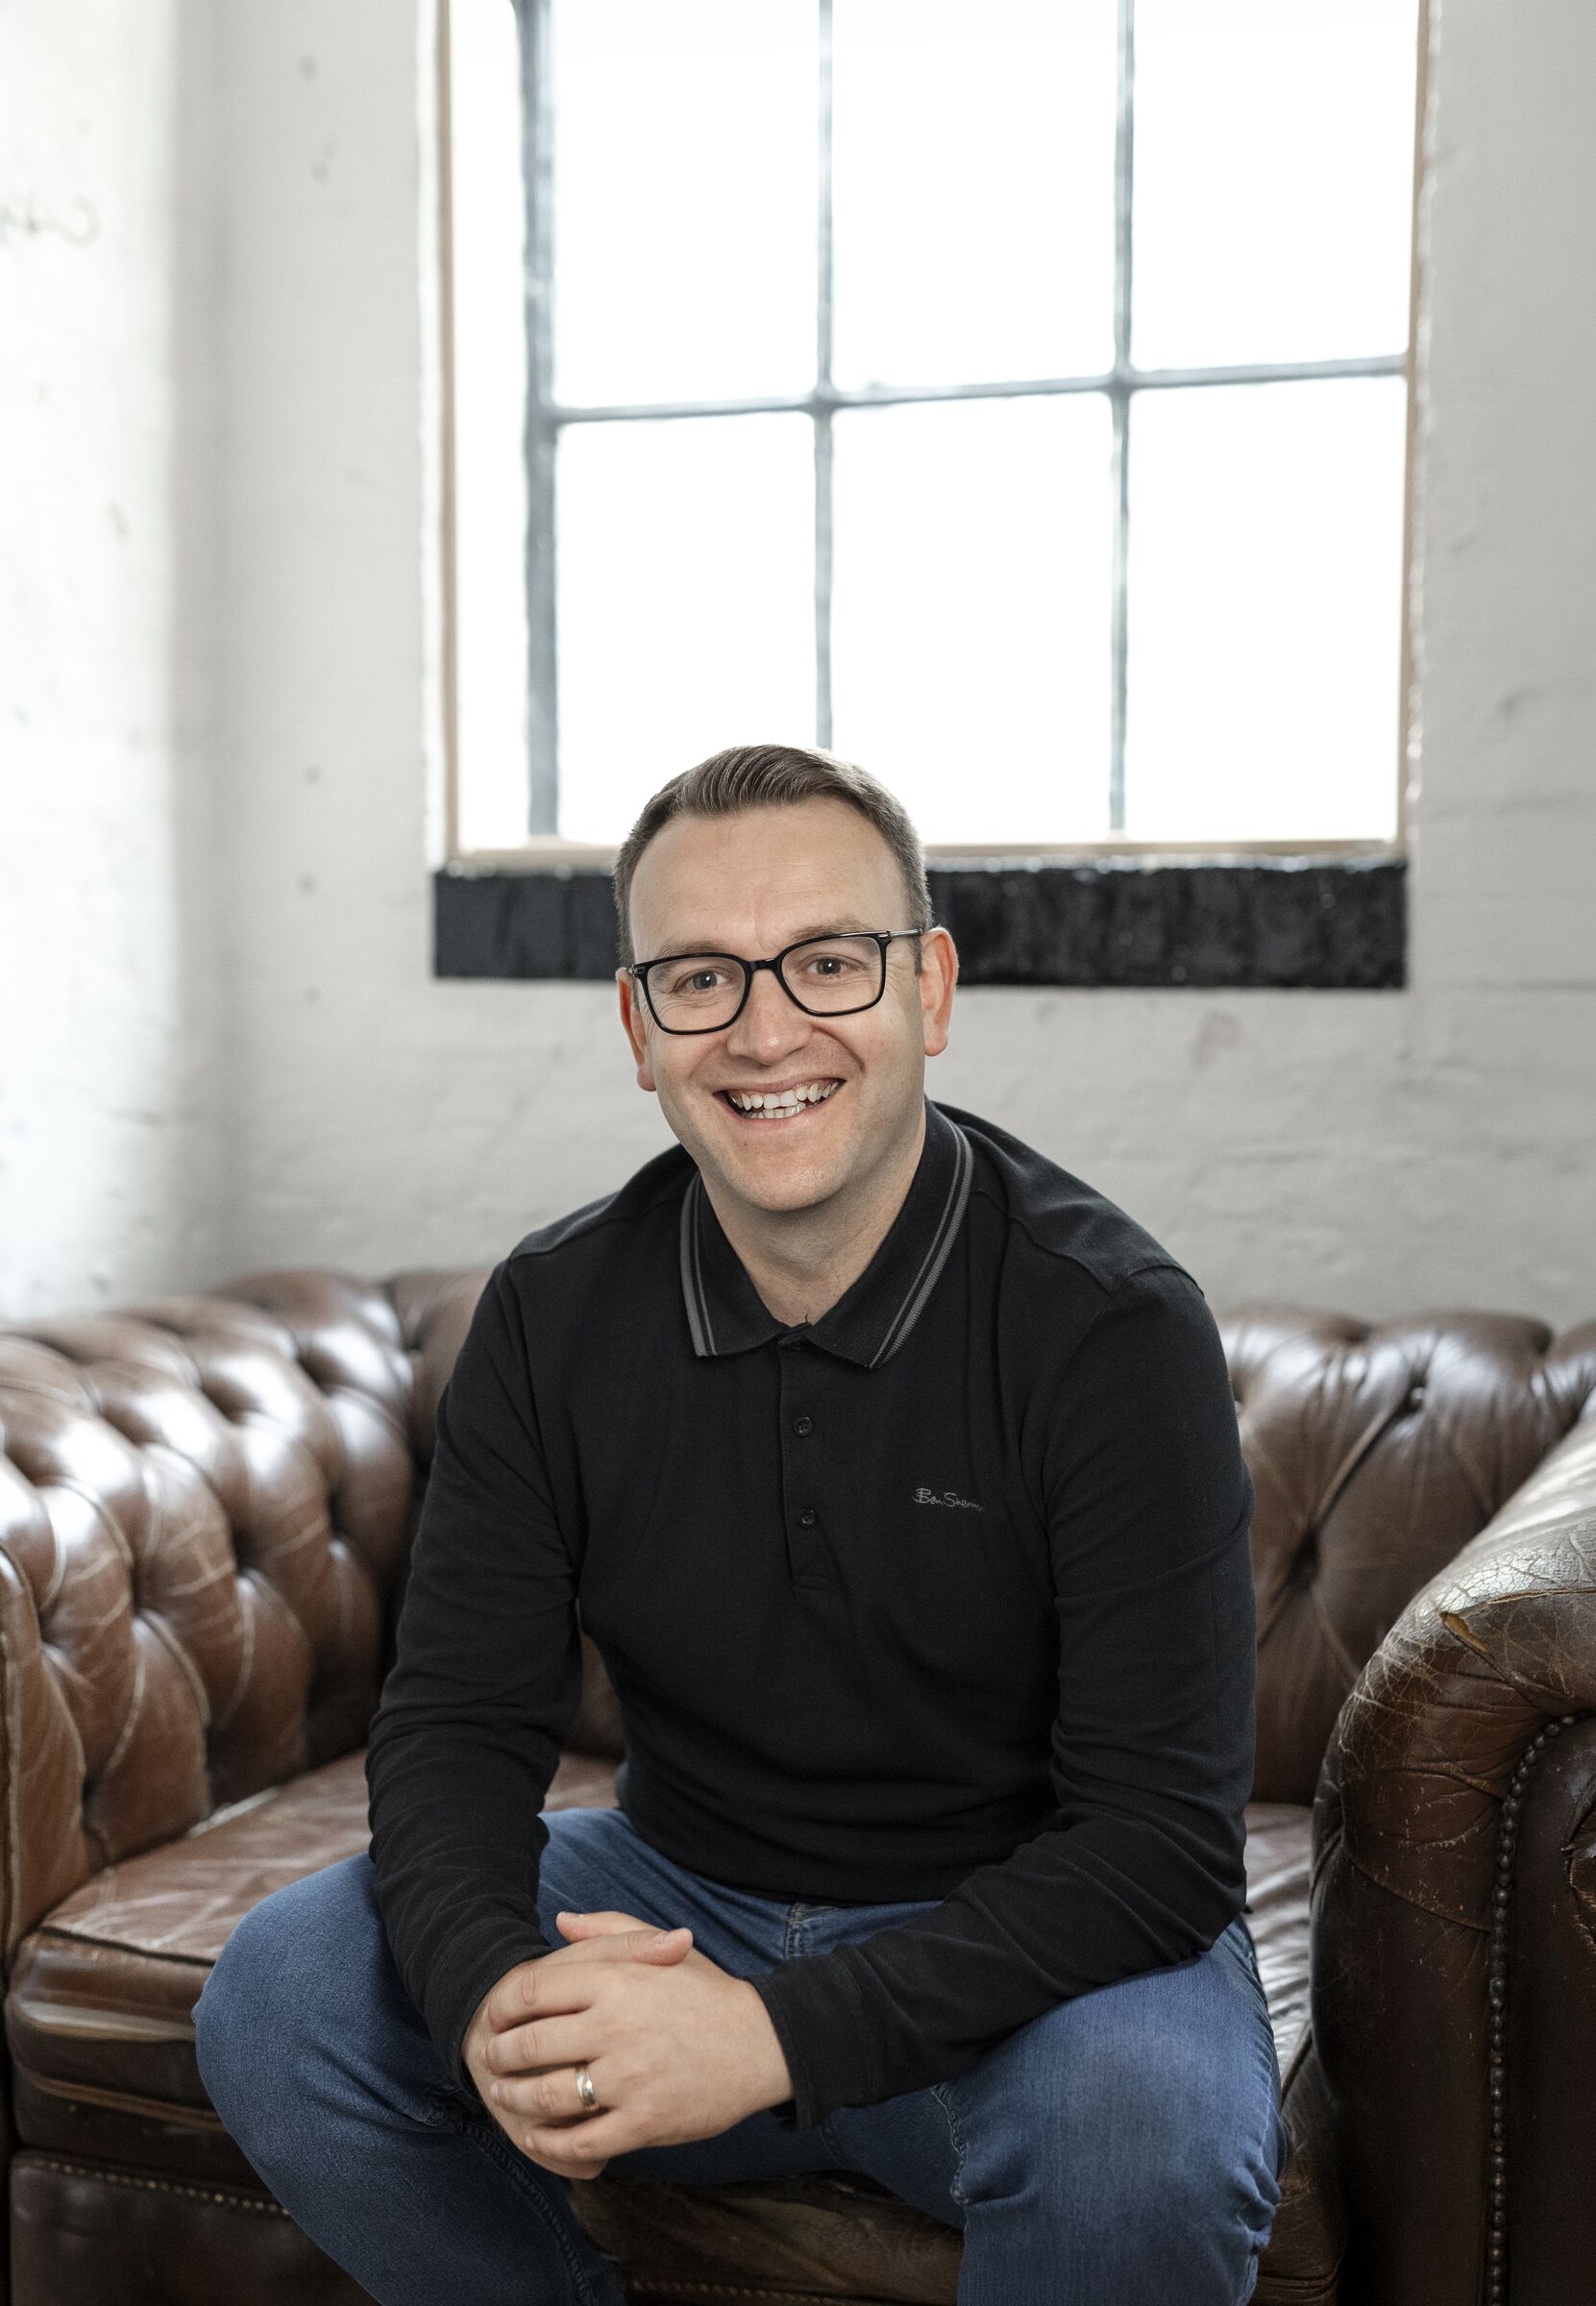


Craig is a corporate and commercial solicitor at Tend Legal, working with founders, business owners and leadership teams as they build, grow and protect their businesses.
He advises on a wide range of matters: mergers and acquisitions, shareholder agreements, company structures, governance and commercial contracts of all kinds. Craig also has a particular interest in intellectual property, and regularly advises on trademark and copyright matters. His IP work has included a matter involving a Premier League and England international footballer, and advising on a copyright assignment connected to a well-known album cover.
Down-to-earth and easy to work with, Craig places a strong emphasis on clear communication and making sure clients feel confident about the decisions they're making. He works closely with agency and commercial clients, acting as an accessible part of their wider advisory team.
Outside of work, Craig is a keen football fan and enjoys spending time with his family.
Neelam is a corporate and commercial solicitor with a practical, no-fuss approach to helping businesses get things done.
On the commercial side, she works with agencies, tech companies and growing businesses on the contracts that underpin their operations: drafting, reviewing and negotiating agreements across a wide range of commercial arrangements. On the corporate side, she assists overseas businesses setting up in the UK and forming UK subsidiaries, and has experience of M&A transactions and investment rounds.
Before qualifying as a solicitor, Neelam had a career in legal technology, including as Director of Global Product at LegalZoom. She brings that perspective to everything she does: a deep understanding of what good legal service looks like from the client's side, and how to deliver it.
She's also unfailingly cheerful. Even on Mondays.
When Neelam isn't at her desk, she can often be found upcycling old furniture in her shed, discovering new eateries or testing out recipes on friends and family.
From the moment she got involved in her parents' businesses at a young age, Nicole knew she had a passion for helping businesses thrive.
A corporate and commercial solicitor, Nicole focuses on the work that matters most to growing businesses: M&A transactions, investment rounds, shareholder agreements and company secretarial support. She also helps clients navigate the commercial side: negotiating and reviewing contracts, advising on joint ventures, and being a steady pair of hands through transactions of all sizes.
Nicole is also working towards an MBA, which tells you something about her character and her love of business. Her advice is grounded in commercial reality, not just legal theory.
When she's not taking care of business, Nicole likes to read, run, play tennis and attend church.
Alistair co-founded Tend Legal with Shona on a simple idea: that small and medium-sized businesses deserve the same quality of legal advice as large companies, without the large firm experience.
As a solicitor with a broad commercial practice, he advises business owners on the full range of issues that come with running and growing a company. That means employment law: advising on settlement agreements, workforce decisions and the day-to-day employment questions that land on founders' desks. It means commercial work: negotiating and reviewing contracts, supplier agreements, and the commercial arrangements that keep a business running. And it means corporate transactions: from business sales and acquisitions to investment rounds, share structures and restructures.
Before co-founding Tend Legal, Alistair was a partner at Woodfords Solicitors in South West London, where he spent over a decade building a reputation for clear, commercial advice to SMEs. He is known for his calm approach, his ability to cut through complexity, and his willingness to give a straight answer.
When not working or acting as taxi driver to his three children, Alistair can be found riding bikes or skateboards, playing various instruments, or at church.
Frequently Asked Questions

An EMI (Enterprise Management Incentive) scheme is a government-approved share option arrangement that gives qualifying employees the right to buy shares in the company at a fixed price. It's designed for smaller, higher-risk trading companies and comes with favourable tax treatment for both the employee and the employer.
To qualify, your company must have gross assets of no more than £30 million, fewer than 250 full-time equivalent employees, and must be carrying on a qualifying trade. Certain industries are excluded, including banking, property development and legal services. The individual employee must also meet eligibility criteria: they must work for the company for at least 25 hours per week or, if less, at least 75% of their working time.
If you're not sure whether your company qualifies, we can advise on this before you commit to anything.
For employees, the main advantage is that there's no income tax or National Insurance on the grant of the option, and no income tax on exercise (provided the option was granted at market value). When the shares are eventually sold, the gain is subject to capital gains tax rather than income tax, and employees may qualify for Business Asset Disposal Relief, which reduces the CGT rate to 10%.
For the company, EMI options can generate a corporation tax deduction equal to the gain made by the employee on exercise. There's no employer NI on the exercise of a qualifying EMI option.
These advantages make EMI significantly more tax-efficient than paying an equivalent cash bonus, for both parties.
The main steps are: agreeing the terms of the scheme, obtaining an HMRC valuation (handled by your accountant or tax adviser), drafting the option agreements, and notifying HMRC of the grant within 92 days. We'll also typically prepare an option plan document that sets out the rules of the scheme.
From instruction to completion, a straightforward EMI scheme typically takes four to six weeks. The HMRC valuation process is usually the main variable: HMRC's turnaround time can fluctuate.
We'll give you a realistic timeline at the outset and keep you updated throughout.
There are other ways to give employees an economic interest in the company's growth. Unapproved options work similarly to EMI options but without the tax advantages: they're simpler to set up but less efficient for the option holder. Growth shares are a different structure: employees receive shares with a low current value but participate fully in future growth above a set hurdle, which can be an effective way of sharing upside without giving away equity in the existing value of the business.
The right approach depends on your company's situation, the people you want to incentivise, and what you're trying to achieve. We'll advise on the options and the trade-offs so you can make an informed decision.
EMI options can only be granted to employees or directors who work for the company. They can't be used to incentivise consultants, freelancers or advisers who aren't on the payroll.
For those individuals, unapproved options or a warrant arrangement may be more appropriate. These can be structured to give a similar economic outcome without the EMI tax wrapper. We regularly advise on adviser and consultant incentive arrangements for growing businesses.